UK to invest over US$9 billion into EV batteries, but must make up 55GWh supply gap

The UK has announced plans to invest £7 billion (US$9.3 billion) into EV battery manufacturing and recycling, but will face a supply gap of 55GWh by 2035.
These are some of the conclusions to be drawn from the latest report from research body New AutoMotive, published this week. ‘The UK’s EV Battery Economy’ looks at announced investments and planned manufacturing capacity in the UK, during a time of strong growth for the country’s EV sector; New AutoMotive figures show that BEVs accounted for 30% of new car registrations in the UK in August, a record figure.
This strong deployment means there is ample appetite for new battery manufacturing work, which has been driven by supportive policy. Chief among these policies is the ZEV Mandate, which came into force in January 2024 and requires vehicle manufacturers to ensure that zero-emission vehicles account for an increasing proportion of sales.
Related:Solid-state vs lithium-ion batteries: EV timeline compared
The policy has helped drive more than £41 billion in new automotive investment and the NewAutomotive report notes that while the policy directly governs domestic sales, the UK’s position as an “export-led vehicle producer” means that the incentivisation of more ZEVs on UK roads will, by extension, incentivise further investments in the UK’s manufacturing sector.
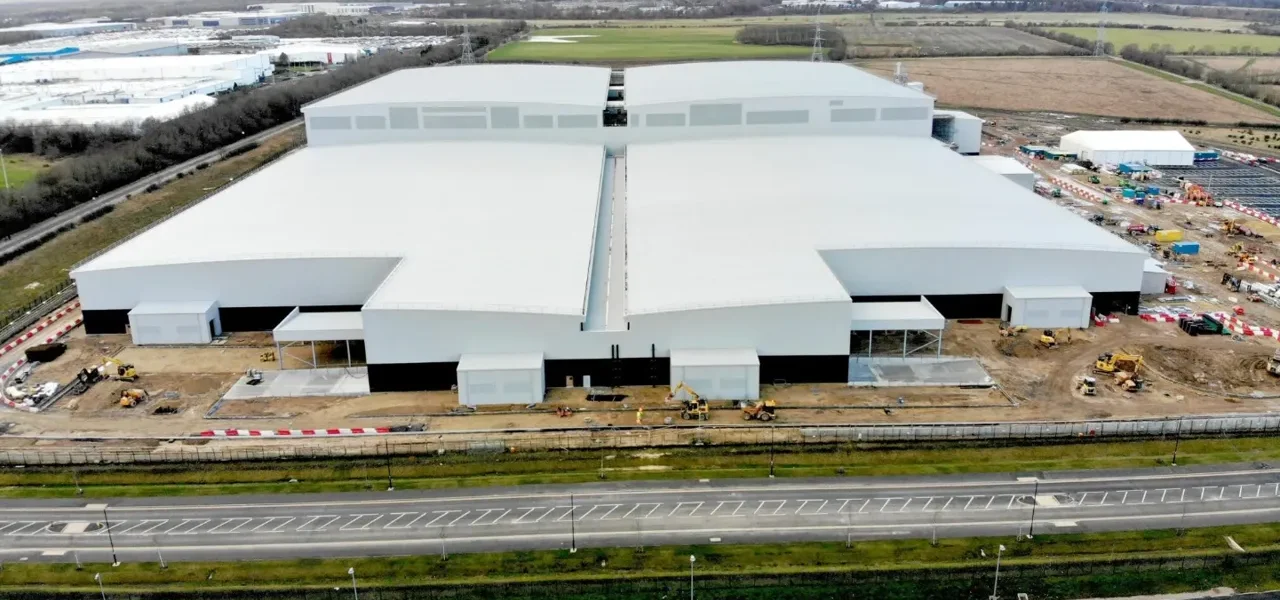
Indeed, the report points to the development a 40GWh battery manufacturing factory by Agratas, part of the Tata Group, as a key source for optimism in the UK battery manufacturing space. This facility was facilitated by a £380 million grant from the government’s DRIVE35 programme, which aims to unlock more than £7 billion of private investment over a ten-year period.
Further upstream, the report also points to strength in the UK’s mining sector, which could help secure a domestic supply of some of the minerals and materials necessary to expand domestic EV manufacturing at scale. Projects from Cornish Lithium and Aberdeen Minerals have collectively secured more than £53 million through a combination of public and private funds to develop mining facilities in the regions from which the companies take their name.
NewAutomotive also notes that recycling is a “real strength” of the UK’s EV market, because the UK is and island and is left-hand drive, so UK EVs at the end of their operational lives are unlikely to be exported overseas and will instead be a “captive future feedstock” for component recycling. The report urges the government to continue its policy commitment to the EV sector, most notably through the ZEV Mandate, to take advantage of these factors and build domestic industries that cover the breadth of the supply chain.
Related:Hyundai reveals battery cells that cut charging time by 40% at 2026 Investor Day
UK remains at an ‘early’ stage of battery manufacturing
Despite the causes for optimism, the report notes that the UK battery supply chain is still at an “early” stage of development, and will need significant expansion in order to meet demand for new batteries. The report points to two manufacturing plants—AESC’s operational 15.8GW facility in Sunderland and the Agratas project that is expected to begin commercial operation in late 2027—as the most mature factories in the UK, with a combined output of just above 30GWh.
This is significantly lower than the annual battery demand of 115GWh that NewAutomotive expects by 2035, should the ZEV Mandate remain in place and encourage further uptake of EVs. The automotive sector will account for around 90% of this demand in 2035, and the report estimates that EV production alone will require 35GWh of batteries, more than double the UK’s current operational battery manufacturing output.
This issue is compounded by the dominance of China in manufacturing across the battery supply chain; the report notes that China produces more than 98% of LFP cathodes, over 90% of graphite anodes and up to 90% of battery cells; in addition, east Asian refineries account for 89% of the world’s hard-rock lithium mining. The disparity between the UK and Chinese industries means that the UK is trying to expand its domestic production at a time where a much more established industry is offering similar products to UK buyers.
For this reason, the New Automotive report calls on the UK government to “maintain the demand signal,” as strong policy support for new EV deployment will make it clear that investing in UK EVs, and the domestic manufacturing of these vehicles, has a strong business case for potential investors.
“Gigafactories are built against decade-long demand forecasts,” reads the report. “A stable ZEV Mandate is the single clearest signal the UK can send.”
The report also calls on the UK to borrow policy directives from the EU, which is facing similar challenges. New AutoMotive points to policies like the EU Battery Regulation, which has driven the industry towards a “data-first battery design” approach and will require EV batteries to have digital battery passports from February 2027; adopting similar policies that concern material traceability and battery deployment could be of benefit to the UK EV battery sector.